A bank may offer the lower-cost loan, but it may not be able to close before a seller accepts another offer. That is the practical difference behind hard money versus bank loans for many Texas investors, builders, and business owners. The right choice is not simply about getting approved. It is about matching the financing to the property, timeline, exit strategy, and level of risk involved.
A conventional bank loan can be an excellent fit for a stable property and a borrower with time to document income, assets, credit, and property condition. Hard money can make more sense when a property needs work, an auction or contract deadline is close, or the borrower plans to repay the loan quickly through a sale or refinance. Each option has real advantages, and each can become expensive when used for the wrong purpose.
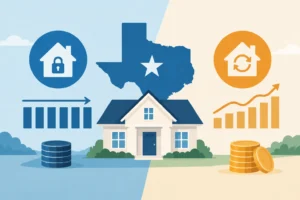
Hard Money Versus Bank Loans: The Core Difference
Bank loans are generally underwritten around the borrower’s financial profile and the property’s current condition. Banks commonly review credit history, debt-to-income ratio, tax returns, bank statements, appraisal results, reserves, and the property’s ability to support the proposed loan. Their rates and terms are often more favorable because the underwriting process is more detailed and the lender is taking a more measured approach to risk.
Hard money loans are asset-based, private loans secured by real estate. A hard money lender is often focused heavily on the property’s value, the investor’s experience, the scope of repairs, and a credible repayment plan. For a fix-and-flip transaction, that may include the purchase price, renovation budget, estimated after-repair value, and projected resale timeline.
That difference changes the entire experience. A bank may be appropriate for a long-term rental acquisition with clean financials and a stabilized property. A hard money loan may be appropriate for a distressed home that cannot qualify for traditional financing in its current condition.
Speed Can Matter More Than Rate
A lower interest rate does not always produce the better outcome if it costs an investor the deal. In competitive Texas markets, sellers may favor buyers who can close quickly and provide confidence that financing will not fall apart late in the process.
Hard money financing is often designed for speed. The process can be more direct because the lender is evaluating a shorter-term, property-secured opportunity rather than underwriting a long-term conventional mortgage. That does not mean documentation disappears. Borrowers should still expect the lender to review the purchase contract, title information, insurance, repair budget, property value, and exit strategy.
Bank financing generally takes longer because more conditions must be satisfied. An appraisal, income verification, credit review, deposit sourcing, property inspections, and internal underwriting can all affect the closing schedule. For a borrower buying a move-in-ready home or refinancing a stabilized property, that timeline may be perfectly acceptable. For an investor trying to purchase a vacant property with a two-week closing requirement, it may not be.
Cost: Look Beyond the Interest Rate
Hard money loans typically carry higher interest rates and lender fees than bank loans. That higher cost reflects shorter loan terms, faster execution, and a greater willingness to consider properties or borrower situations that fall outside standard bank guidelines.
A bank loan may have a lower rate, lower fees, and a longer repayment period. That can make it the clear financial winner for a borrower who intends to hold the property for years. It can also support more predictable monthly cash flow, especially for a rental property with steady occupancy.
The key is to evaluate total financing cost over the actual holding period. A higher-rate hard money loan used for four or five months may be reasonable if it allows an investor to buy, renovate, and sell a profitable property. The same loan can become a problem if renovations run late, resale demand slows, or the borrower has no backup plan for refinancing.
Borrowers should account for interest, origination fees, points, appraisal or valuation costs, title charges, insurance, extension fees, prepayment terms, draw fees for construction funds, and potential default charges. A loan that looks attractive from one number alone can be misleading.
Property Condition Often Determines the Path
Traditional lenders generally prefer properties that are habitable, marketable, and easy to appraise. A home with major foundation work, extensive water damage, unfinished construction, code issues, or substantial deferred maintenance may not meet conventional property standards. Commercial properties can present similar challenges when occupancy is low, financial statements are inconsistent, or repairs are significant.
Hard money lenders may be more willing to finance a property with problems because the loan is structured around the opportunity to improve it. The property itself is not ignored. In fact, it is central to the decision. But a lender may be willing to look at projected value after repairs rather than relying only on the property’s current condition.
This is why hard money is common in fix-and-flip financing, bridge loans, renovation projects, inherited properties, and acquisitions requiring fast action. It is not a replacement for conventional financing in every situation. It is a specialized tool for transactions that do not fit a standard box.
Underwriting: Personal Income vs. the Deal Itself
Bank underwriting usually places substantial weight on the borrower’s ability to repay from documented income and assets. Strong credit, manageable debt, stable earnings, and adequate reserves can make a major difference. For business and commercial borrowers, lenders may also review tax returns, profit-and-loss statements, balance sheets, debt-service coverage, and business history.
Hard money lenders still evaluate the borrower, but the focus may be more practical: Does the borrower have a meaningful down payment? Is the renovation budget realistic? Does the estimated after-repair value support the loan? Has the borrower completed similar projects? Is the exit plan supported by market conditions?
A newer investor should not assume hard money means automatic approval. Inexperienced borrowers may be asked to bring more cash to closing, provide a detailed contractor bid, show reserves, or work with an experienced partner. The lender wants evidence that the project can be completed and the loan can be repaid as planned.
The Exit Strategy Is Not Optional
A hard money loan is usually short-term. Before closing, the borrower should be able to explain exactly how it will be paid off. Common exits include selling the renovated property, refinancing into a conventional or investment-property loan, selling another asset, or paying the balance from verified cash reserves.
Refinancing deserves special attention. If the plan is to refinance after repairs, the borrower should consider whether future credit, income, property condition, rental income, and appraisal value are likely to support that new loan. A refinance is not guaranteed simply because the renovation is complete.
With a bank loan, the repayment plan is generally built into the longer-term structure. Even then, borrowers should consider whether the payment fits during vacancies, rate adjustments, slower business revenue, or unexpected repairs. Financing should support the project, not force the project to perform perfectly every month.
When a Bank Loan Is Usually the Better Fit
A bank loan is often the stronger choice when the property is in good condition, the borrower has sufficient time to close, and the financing will be held for the long term. It is also usually worth pursuing when a borrower has established income, solid credit, and a property that meets conventional appraisal and condition requirements.
For owner-occupied homes, stabilized rentals, established businesses, and long-term commercial real estate, lower-cost bank financing can preserve cash flow and reduce the total cost of borrowing. The slower process may be a reasonable trade-off for better terms.
When Hard Money May Be the Better Tool
Hard money may be appropriate when speed, property condition, or a short-term opportunity makes conventional financing impractical. Investors commonly consider it for fix-and-flip projects, properties purchased below market value, homes requiring major repairs, short-deadline acquisitions, and bridge financing while permanent financing is arranged.
The strongest hard money transactions have a clear margin for repairs and carrying costs, a conservative value estimate, an experienced team, and a realistic exit. Borrowers should be cautious when the deal only works if every repair stays on budget and the property sells immediately at the highest projected price.
Ask the Right Questions Before You Commit
Before choosing a lender, ask how long the loan term is, whether payments are interest-only, how renovation draws are handled, what happens if the project needs more time, and whether there are extension or prepayment fees. Confirm the rate, points, required cash contribution, and estimated closing costs in writing.
It is also wise to ask what assumptions support the property’s value. For a flip, review comparable sales carefully. For a rental refinance, estimate income conservatively. For a commercial project, evaluate occupancy, operating expenses, and debt payments under less-than-perfect conditions.
Vision Mortgage Company helps Texas borrowers evaluate conventional, commercial, investment-property, construction, and private financing options based on the transaction at hand. The best loan is the one that gives you a workable path from purchase to payoff, with costs and timing you can realistically manage.